Published October 6, 2026

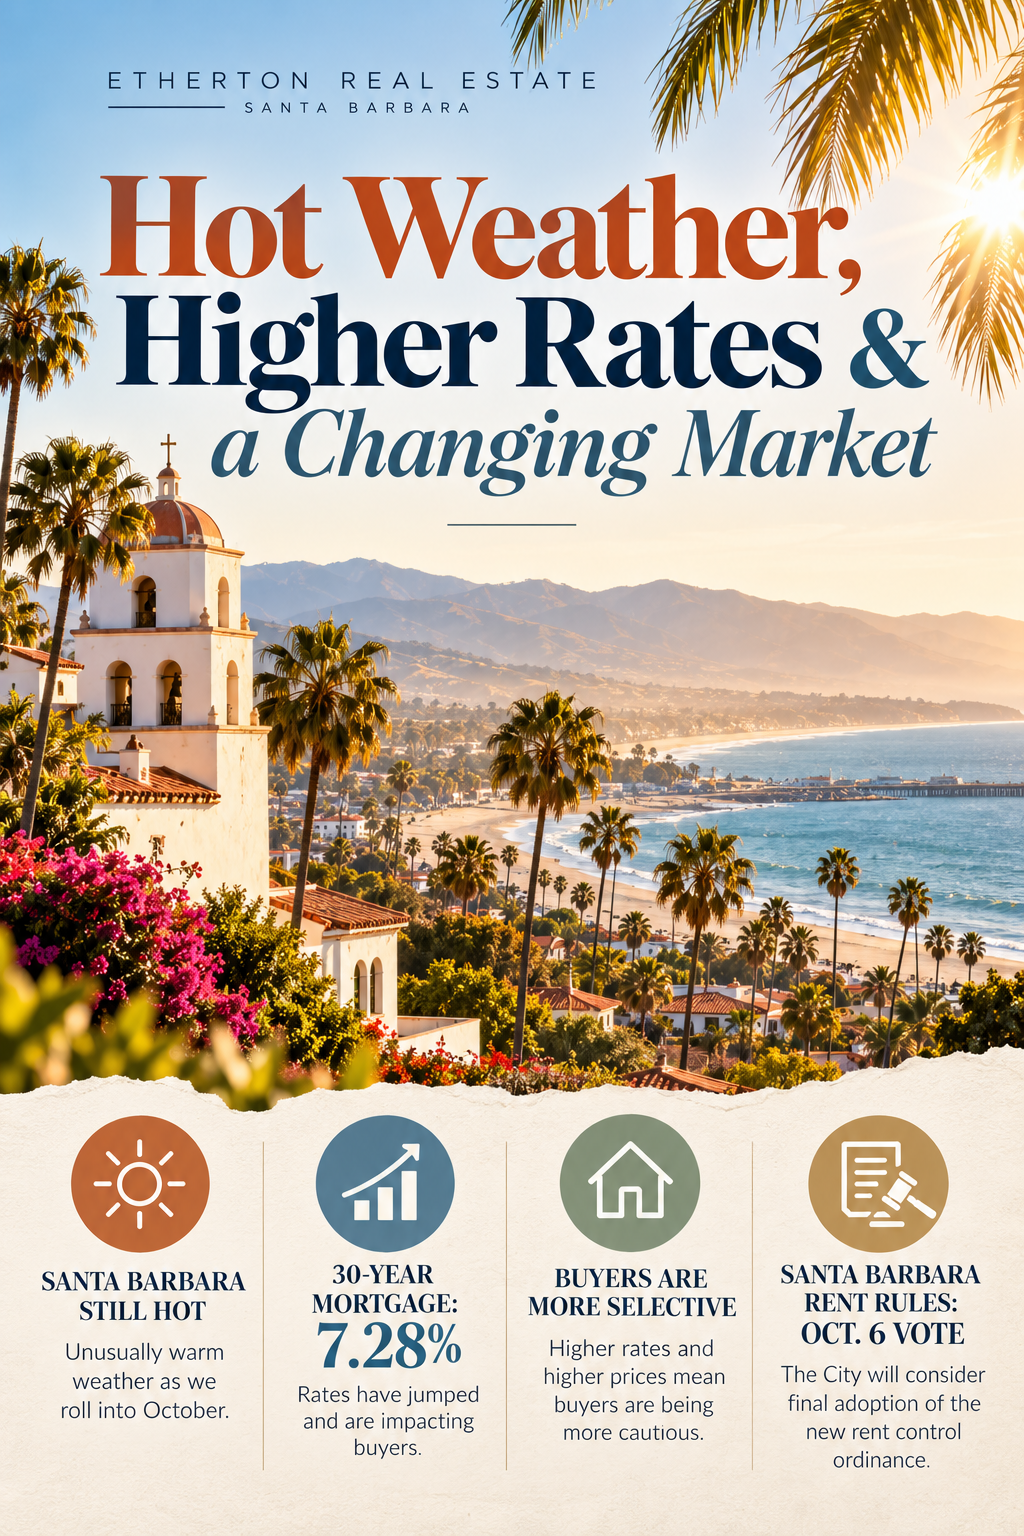
Hot Weather, Higher Rates & a Changing Market

Author Avatar

Written by Justin Etherton

πŸ”₯ Hot Weather, Higher Rates & a Changing Market

πŸ”₯ How Are You Staying Cool in This Crazy Heat?


October is here, and normally we'd expect crisp mornings, cooler evenings, and signs that fall has finally arrived.

Instead, Santa Barbara has given us blistering heat and even some sticky humidity! β˜€οΈ

I'm definitely thankful for a few things right now—air conditioning, solar panels, our community pool, and of course the beach. 🌊 Solar makes running the AC a little less painful when the electric bill arrives, and living this close to the ocean certainly has its benefits on days like these.

Hopefully cooler temperatures—and some much-needed rain—are around the corner.

But the weather isn't the only thing that's been unpredictable lately...


🏑 Higher Rates Are Changing the Market

Interest rates have moved higher again, and we're seeing the impact on buyers in real time.

Just last week, a lender shared a story with me about a buyer who hadn't locked their interest rate because some paperwork hadn't been uploaded.

Within about 24 hours, the rate moved nearly half a percentage point.

That may not sound like much, but on a Santa Barbara-sized mortgage, it can significantly change a monthly payment—and in some cases, it can be enough to jeopardize the entire transaction.

That's the market buyers are navigating right now.

You can read reports saying the economy is doing well, but when I talk to people, many aren't feeling it.

β›½ Everyday expenses remain high
πŸ“ˆ Mortgage rates have climbed
🏑 Home prices haven't fallen enough to offset those rates
πŸ’° Purchasing power has taken a hit

Buyers are understandably cautious.


πŸ€” Is the Market Shifting?

Housing markets across the country are becoming more favorable to buyers.

Santa Barbara, however, tends to operate a little differently.

We have two things working strongly in our favor:

LOW INVENTORY + HIGH DESIRABILITY

There are only so many homes available, and there are still a lot of people who want to live here.

Can you blame them? I can't. 😎🌴

That scarcity helps insulate Santa Barbara from some of the larger swings we see elsewhere.

But insulated doesn't mean immune.

Today's buyers are asking a very reasonable question:

"Why would I take on a 7%+ mortgage AND pay a premium price unless this is the right house?"

And that's changing buyer behavior.

Buyers haven't disappeared. They're simply becoming more selective.


🎯 What Does That Mean for Buyers & Sellers?

BUYERS πŸ”‘

Don't automatically assume higher rates mean you should stop looking.

A slower or more challenging market can create opportunities that didn't exist when every home had 10 offers.

Look for:
βœ… Price reductions
βœ… Homes sitting longer
βœ… Motivated sellers
βœ… Properties other buyers overlooked
βœ… Opportunities to negotiate

You may not love the interest rate—but you might love the deal.

SELLERS 🏑

The days of simply putting a home on the market at an aggressive price and waiting for buyers to fight over it are becoming less common.

Price matters. Condition matters. Presentation matters.

The goal is to make buyers walk through the door and think:

"This is the one."


⚠️ Santa Barbara Landlords: Pay Attention

There is another major real estate issue developing in Santa Barbara.

On September 29, the Santa Barbara City Council voted 4–3 to formally introduce a permanent rent stabilization ordinance and citywide rental registry.

Final adoption is scheduled for October 6.

If adopted as currently drafted, some of the major provisions include:

πŸ“Œ Rent Caps: Annual increases limited to 60% of CPI, with a maximum of 3%.

πŸ“Œ No Banking: Unused increases cannot be saved and used in future years.

πŸ“Œ Rental Registry: Most rental properties would be required to register with the City.

πŸ“Œ Limited Exemptions: Certain single-family homes, condominiums, newer construction, and other qualifying properties may be exempt from portions of the ordinance.

πŸ“Œ Rent Stabilization Board: A seven-member board would hear appeals, with at least four seats designated for tenants.

πŸ“Œ Petition Process: Procedures would be created for tenant petitions, capital improvements, and constitutionally required fair-return increases.

πŸ“Œ Temporary Relocation: Qualifying temporary displacements could trigger lodging and meal payments.

πŸ“Œ Implementation: The permanent program is currently scheduled to begin January 1, 2027.

This is a substantial change for Santa Barbara rental-property owners, and the details and exemptions matter.

If you own rental property in the City of Santa Barbara, I strongly recommend understanding how the final ordinance applies to your specific property before making decisions about rents, improvements, selling, or future investments.


🏑 The Bottom Line

We're entering an interesting real estate market.

Buyers are cautious.
Rates are high.
Some prices are softening.
Inventory remains limited.
And Santa Barbara remains an incredibly desirable place to live.

That creates both challenges AND opportunities.

I'll continue watching the numbers and keeping you updated as the market evolves.

If you're thinking about buying, selling, or investing—or you're a landlord trying to understand how these changes may affect your property—give me a call.

Let's build a strategy.

— Justin Etherton
Etherton Real Estate Group


Americans hoping for an ’08-style housing crash to afford a home are out of luck
California Post
Emily Fu

Those holding out hope for a housing crash are setting themselves up for disappointment.

American home prices would need to plunge nearly a third to make today’s punishing mortgage rates as affordable as the loans millions of existing homeowners are sitting on.

The median US home sold for $429,100 in August, but at today’s mortgage rates, that price would have to tumble 32% to about $291,181 for a new buyer’s monthly payment to match that of the typical current mortgage holder, according to a new Barron’s analysis.

To put that staggering figure in perspective, US home prices fell about 27.5% from their 2006 peak through September 2010 amid the housing crash and financial crisis, according to Federal Reserve data — meaning a 32% plunge would be even worse.

Nadia Evangelou, director of research at the National Association of Realtors, told Barron’s she doesn’t expect prices to fall by anything close to that amount.
 

The brutal math illustrates just how dramatically the surge in borrowing costs has reshaped the housing market — and why homeowners who locked in rock-bottom rates during the pandemic have so little incentive to move.

The typical existing mortgage holder has a 3.88% rate and pays $1,597 a month, according to ICE Mortgage Technology data cited by Barron’s.

But mortgage rates have recently surged to around 7.3%.

At that rate, a buyer putting 20% down on the $429,100 median-priced home would face a monthly principal-and-interest payment of about $2,353 on a 30-year mortgage, Barron’s calculated.

That’s $756 more every month — or roughly 47% higher — than the median payment shouldered by current mortgage holders.
 

To get that payment back down to $1,597 without a drop in rates, the home’s price would need to sink to roughly $291,181.

The enormous gap helps explain the so-called mortgage-rate lock-in effect that has dogged the housing market since borrowing costs began climbing.

Millions of Americans refinanced or purchased homes when mortgage rates plunged during 2020 and 2021. Those loans have become increasingly valuable as prevailing rates have more than doubled.

Rick Palacios Jr., director of research at John Burns Research & Consulting, described those ultralow pandemic-era mortgages as becoming a “generational scourge” as they discourage homeowners from putting their properties on the market.

The result has been a stubborn shortage of existing homes for sale in many parts of the country, even as would-be buyers struggle with a combination of elevated prices and borrowing costs.

And homeowners hoping that mortgage rates will simply return to pandemic-era levels may be waiting a while.

Persistent inflation and elevated bond yields offer little reason to expect a dramatic decline in mortgage rates in the near term, according to Barron’s.

A 32% collapse in home prices isn’t the expected solution, either.

Evangelou says affordability is more likely to improve gradually through some combination of lower mortgage rates, rising incomes and slower home-price growth.

 
...

Read the Full Article Here!

Gen Z Is Holding Out for Sub-5% Mortgages. It’s In for a Rude Awakening 
Realtor.com
Dina Sartore-Bodo

The narrative blaming young adults for their inability to become homeowners is as persistent as it is tired: If Gen Z would simply stop spending money on dining out, shopping, and luxury experiences to flaunt on social meda, the door to homeownership would magically fly open. 

But all this finger-pointing ignores fundamental truths about the economy. In short, Gen Z is not failing to buy homes because they refuse to make sacrifices; they are priced out by a compounding web of structural barriers.

In fact, young adults are more willing to compromise than critics give them credit for. Most are more than willing to give up their “little treats” for a shot at the American dream.
 

However, there is one big obstacle standing in their way that they can work on: a very skewed perception of mortgage rates now and in the future.

Future homebuyers facing the present reality

The next generation of homebuyers is actually more flexible than some of their harshest critics would give them credit for. 

According to a recent report by Cotality, 78% of Gen Z homebuyers say they would willingly cut lifestyle spending to afford a home. Moreover, 74% are prepared to compromise on square footage, accepting a smaller home just to secure a mortgage. 
 

Still, the younger generation has a hard line when it comes to their housing journey. The same report found that 40% of Gen Z future homebuyers are waiting on a specific mortgage rate to buy—and for young buyers, that number is 4.9%.

Given that the current mortgage rate stands at 7.28%, it’s safe to say that this generation has a wait on its hands.

“Freddie Mac's Oct. 1 release put the 30-year fixed rate [at its] highest since November 2023 and nearly a full percentage point above a year ago,” explains Hannah Jones, senior economist with Realtor.com®. 

“Mortgage rates typically move less than 1 percentage point in either direction over 12 months, so a drop below 5% would require a far larger swing than usual.”

But it’s not just Gen Z. The median rate that would spur on future buyers of any age—millennial, boomer, etc.— is 4.5%, a rate more in line with the plunge during COVID-19 and not with the industry at large. 

In short, everyone, including Gen Z, would benefit from a bit more perspective when it comes to rates. 

“We don't expect rates to fall below 5% in the next year, and longer-range forecasts don't show sub-5% rates in the next few years either,” adds Jones.  “The low- to mid-6% range is a more realistic medium-term outlook, unless something sharply negative, like a recession, pushes rates lower.”


Map showing markets where Millennials and Gen Z buyers own the most housing wealth


...

Read the Full Article Here!

 Inside the rise of California's new housing compounds
 

SF Gate
Tessa McLean

When East Bay resident Dana Gersten found out she was pregnant with her first child, she knew she didn’t want to raise the child alone. She wasn’t single — she has a loving, devoted partner — but she envisioned her baby growing up surrounded by a supportive community, ideally in a communal housing environment where people share resources and help one another day to day. 
Co-living situations weren’t new to Gersten. She’d opted for them during college and would go on to reside in different versions of them during and after medical school. She loved the spirit of these places, sharing responsibilities like cooking and home maintenance and always having someone around for a chat. But this time, as she searched for the right community, she couldn’t find a fit. Unable to see a path to
homeownership in the Bay Area without co-living, she decided to create her own version — with her friends. 
Gersten is part of a new generation of Californians opting to purchase real estate with more people than the typical family unit, as soaring home prices shut out many potential buyers. For some, it’s the only way they can afford property, and for others, their budget wouldn’t get them the home they desire. Backed by changes to mortgage lending and new
California regulations, the interest in creating a compound-like living situation is growing. 

From friend to co-owner 

Once Gersten and her partner made the decision to buy property with friends, she didn’t expect the process to take as long as it did. They looked with three separate groups, and “none of it panned out,” she said. One ended up being worried they’d ruin their friendship over it, while the others couldn’t align on a property after dozens of showings. But on their fourth friend attempt, they found a match, and they now live together in a duplex in Berkeley that’s owned as two separate condos. Eventually, the group wants to build at least one accessory dwelling unit, or ADU, on the property, to add more people to their community.
It wasn’t easy, but Gersten said it was worth it. Their friend in the other unit is “like an uncle” to their now two kids. And their situation solves the biggest problems people who live in major cities face: the high cost of housing and the loneliness of living far from family and friends. 

“Most parts of the world people live a lot more communally and closer to their family, and there’s a lot more integration,” she said.

Now that Gersten is building her own community, she’s fielded a lot more questions from people about her living situation. “I feel like even my very non-hippie friends are really intrigued about this idea,” Gersten said with a laugh.

Interest does seem to be growing. A 2022 Zillow survey found that 18% of homebuyers surveyed had purchased with a friend, and 19% of prospective buyers planned to buy with a friend or relative in the next year. A Remax/Pollfish survey released in January 2024 found that 27.7% of prospective buyers would consider purchasing with a friend or family member.

Making communal ownership work

Friends and family who purchase property together often enter into a tenancy-in-common agreement, a legally binding document that includes rules and financial responsibilities. New data from Redwood Credit Union, a Bay Area financial institution that offers TIC financing, saw TIC lending grow 79% between July 2024 and June 2026. Debbie Ingle, a senior vice president of mortgage lending at the bank, said interest has “moved at warp speed,” especially as awareness has grown. 

...

Read the Full Article Here!

What people are saying!
Here are some of our recent client testimonials!


Click here for more info!


ANOTHER SUCCESS STORY!!!

Accepted Offer!!!!! Congratulations to Joe and Maria! They have been looking for a long time with me (a couple of years now). We found a great home and this is only the 3rd time we have made an offer. The offer was aggressive and way under the asking price. We negotiated the heck out of it and go the seller to come way down and allow it to be contingent on selling their home. Needless, to say Joe and Maria are thrilled.


Coming Soon And Off Market Properties!

See all the current properties that are not yet on the market. Send us an email and we can start sending you these properties daily.

I have an off market Mesa home and Goleta Condo getting ready to come on the market. 

Here's What's Happening This April!

 Palm Tree Music Festival
@SB Polo Fields
Oct 10th-11th


Ride Santa Barbara 100
SB 
October 17th

Fields Of Faith
SBHS
10/14 6:45


Boo at the Zoo
10/23-10/25
@The SB Zoo

Copyright © 2026 Etherton Real Estate, All rights reserved.
You are receiving this email because you opted in via our website.

Categories

Buying Process, Market update, Selling Process, Things to do in Santa Barbara

or another way