|
|
|
|
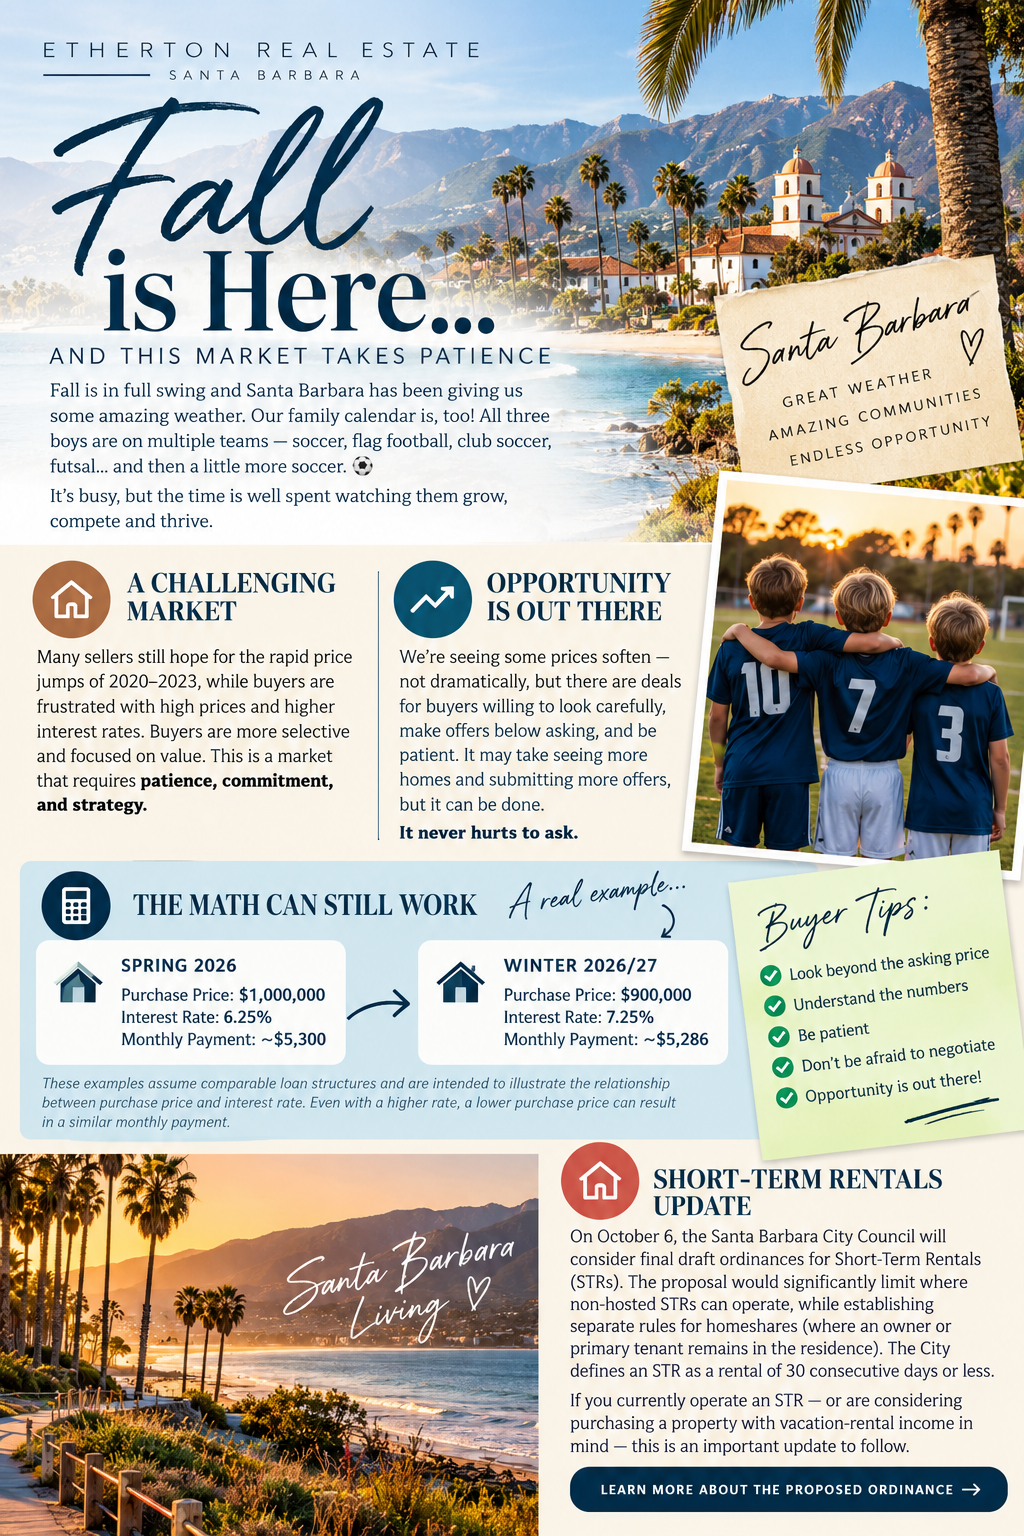
🍂 Fall Is Here… and This Market Takes Patience
Fall is in full swing, and Santa Barbara has been giving us some incredible weather to enjoy.
Our family calendar is also in full swing. All three boys are currently on multiple teams playing some combination of soccer, flag football, club soccer, futsal… and then a little more soccer. ⚽😂
It's busy, but the time is well spent. Watching our kids grow, compete, learn, and thrive in school and sports is something I wouldn't trade.
The real estate market, however, has been a little more challenging.
🏡 Are You Feeling It Too?
Are you trying to sell your home but finding that buyers have become pickier?
Are you thinking about buying but wondering if you should wait because interest rates haven't come down—and recently have actually moved higher?
You're not alone.
This has been a challenging market for a lot of people.
Many sellers still remember the rapid appreciation of 2020–2023 and want to see their homes continue climbing at that pace.
Meanwhile, buyers are frustrated with the combination of high home prices AND high interest rates.
The result?
Buyers are becoming much more selective. They're willing to move—but they're focusing on the homes they perceive as offering the best value.
This is a market that requires patience, commitment, and strategy.
💰 Buyers: Learn the Math Before Sitting on the Sidelines
Higher interest rates are frustrating. There's no way around that.
But we're also beginning to see some prices soften. I'm not saying Santa Barbara home prices are suddenly dropping dramatically—they aren't.
But there are deals out there if you're willing to look for them.
That may mean:
🔎 Looking at more properties
💵 Making offers below asking
📝 Writing more than one offer
⏳ Being patient
🏚️ Looking at homes other buyers have overlooked
Here's a real-world example:
I had a client interested in a fixer listed around $1.1 million. He didn't make an offer because the property needed significant work and he assumed the seller wouldn't accept what he was willing to pay.
It eventually sold for approximately $750,000—less than my buyer would have paid.
Ouch.
The lesson?
It never hurts to ask.
🧮 Here's Where the Math Gets Interesting
Let's use a hypothetical example:
Spring 2026
🏡 Purchase Price: $1,000,000
📈 Interest Rate: 6.25%
💰 Approx. Principal & Interest: $5,300/month
Winter 2026/27
🏡 Purchase Price: $900,000
📈 Interest Rate: 7.25%
💰 Approx. Principal & Interest: $5,286/month
That's a 10% lower purchase price, but even with an interest rate that's a full percentage point higher, the approximate monthly principal-and-interest payment is essentially the same.
These examples assume comparable loan structures and are intended simply to illustrate the relationship between price and interest rate.
Do I think Santa Barbara homes across the board are dropping 10%? No.
But we're seeing enough softening on certain properties that buyers shouldn't automatically assume a higher interest rate means there isn't an opportunity.
Sometimes the better strategy is to negotiate the purchase price today and refinance later if rates eventually improve.
🏖️ Big Changes Proposed for Santa Barbara Short-Term Rentals
There's another local real estate issue worth watching closely.
On October 6, the Santa Barbara City Council is scheduled to consider final draft ordinances regulating Short-Term Rentals (STRs).
The proposal would significantly limit where non-hosted STRs can operate while establishing separate rules for homeshares, where an owner or primary tenant remains in the residence.
This could be particularly important for property owners in residential neighborhoods, including portions of the coastal zone.
If you currently operate an STR—or are considering purchasing a property with vacation-rental income in mind—pay attention to this one.
One important distinction: the City's proposal defines an STR as a rental of 30 consecutive days or less. That means furnished rentals structured for longer stays are an important separate category to understand.
👉 Click HERE to learn more about the City's proposed Short-Term Rental Ordinance.
The Bottom Line 🎯
This isn't an easy market.
But a challenging market doesn't mean there aren't opportunities.
For sellers: Pricing and presentation matter tremendously.
For buyers: Don't assume the asking price is the selling price. Learn the numbers, stay patient, and don't be afraid to make an offer.
Sometimes the opportunity everyone else overlooks is the one worth pursuing.
If you're thinking about buying, selling, or investing in real estate, let's connect and build a strategy for today's market.
— Justin
Etherton Real Estate Group
|
|
Florida, Texas, and California Lead the Nation in Foreclosure Starts
Realtor.com
By Julie Gerstein
Foreclosure activity continued an upward trajectory in August, with data showing both monthly and annual increases—although foreclosures remain well below crisis levels.
Overall, 40,277 properties were involved in foreclosure filings in August—up 1% from July 2026 and 13% from August 2025—according to the August 2026 U.S. Foreclosure Market Report released by property data provider ATTOM. These properties either received default notices, were scheduled for auction, or were repossessed by banks.
“August’s data shows that foreclosure activity continues to trend above year-ago levels, particularly in completed foreclosures, which saw a notable annual increase,” said Rob Barber, CEO of ATTOM. He noted that “overall foreclosure volumes remain well below historical norms and the broader housing market continues to demonstrate resilience.”
On the state level, Florida led the nation in new foreclosure starts with 3,189 filings, followed closely by Texas with 3,126 starts and California with 2,565 starts. Illinois and Georgia rounded out the top five states for foreclosure starts, recording 1,192 and 1,189 starts, respectively.
Meanwhile, South Carolina, Nevada, and Florida had the highest per capita foreclosure rates. South Carolina had 1 filing for every 1,547 housing units, Nevada had 1 filing for every 1,920 housing units, and Florida saw a foreclosure start rate of 1 in every 2,397 housing units.
Texas and Maryland completed the top five states with the highest overall concentration of distress, recording 1 foreclosure filing for every 2,445 and 2,530 housing units, respectively. Nationally, 1 in every 3,569 housing units had a foreclosure filing in August 2026.
Among major metro areas with populations of at least 200,000, Columbia, SC, had the highest foreclosure rate in the country, with 1 foreclosure filing for every 1,232 housing units.
Punta Gorda, FL—the metro with the highest foreclosure rate in July—followed closely, with 1 filing for every 1,249 housing units. Spartanburg, SC, saw 1 foreclosure for every 1,262 units; Fayetteville, NC, had 1 for every 1,458 units; and Charleston, SC, had 1 for every 1,501 units.
Some metro areas recorded foreclosure declines, however. Among metropolitan areas with populations of at least 200,000 and at least 50 foreclosure starts, Cleveland saw the largest year-over-year decline, dropping from 281 starts in August 2025 to 175 in August 2026. Other notable metro areas seeing declines included Washington, DC; Providence, RI; Raleigh, NC; and Kansas City, MO.
....
Read the full Article Here
|
|
Builders proceed cautiously with single-family home construction
Elevated material costs, high energy prices and labor shortages are continuing to pressure the construction market, with builder confidence now at a 2026 low.
Real Estate News
By Dave Gallagher
Builders appear to be proceeding with caution as they gauge demand for new homes — but if the residential construction industry is going to see momentum anytime soon, it will need to catch a break on the current cost environment that is pressuring builders and consumers alike.
Single-family housing starts rise: Overall housing starts in August fell 2.6% compared to July, according to the U.S. Census Bureau. However, single-family home starts were up 7.6% month-over-month and up 5.2% compared to a year ago, with the seasonally adjusted annualized rate coming in at 918,000.
The past six months of data suggest that housing starts have stabilized, though new home construction permits and completions continue to trend lower, according to Mark Fleming, chief economist at First American.
"Permits lead actual construction, so the August data suggests builders are modestly tightening the construction pipeline while cautiously starting to build already permitted projects," Fleming said.
As is the case with the existing home market, elevated mortgage rates and high home prices are creating headwinds for consumer demand. "For homebuilding to regain momentum, builders need some improvement in affordability and relief from the costs that continue to squeeze new construction," Fleming said.
Builders remain pessimistic: Builder confidence in September fell three points to 32 — the lowest level since this time last year, according to the National Association of Home Builders' (NAHB) latest Housing Market Index. The monthly gauge has stayed below 50 for over two years.
The NAHB noted that 38% of home builders cut prices this month, a small uptick from 35% in August, though the average price cut held at 6%. Two-thirds of builders also reported that they are offering incentives in an effort to entice buyers.
"Buyer traffic has weakened across much of the country, largely because of rising mortgage rates," NAHB Chief Economist Robert Dietz wrote in a Sept. 16 blog post. "Builders also continue to face higher material costs, rising gas and diesel prices and persistent labor shortages. In some markets, builders report that increased immigration enforcement is discouraging legal workers from reporting to job sites."
...
Read the full Article Here
|
|
California Passes Nation’s First Insurance Requirements for Smoke Damage Claims
Realtor.com
By Tristen Navera
California Gov. Gavin Newsom signed into law a spate of bills to reform the state's wildfire insurance sector, after consumer fallout from the catastrophic Eaton and Palisades fires of early 2025.
The four bills signed in Sacramento on Tuesday are aimed at adding consumer protections for wildfire survivors. The state's home insurance crisis is especially acute as thousands of homes are at high wildfire risk.
Two of the bills aim to codify protections and remediation for smoke damage, and two more give wildfire survivors more leeway to seek mortgage forbearance on homes that are rendered uninhabitable by wildfires.
Increasingly damaging wildfires have resulted in a fraught situation for California, where insurers paid over $22.4 billion in claims in 2024. The state is investigating two insurers, alleging they systematically delayed and underpaid claims. One of theme, State Farm, has called the state's insurance marketplace "dysfunctional."
"We are continuing to listen, act, and stand alongside the families and communities rebuilding after the Eaton and Palisades fires," Newsom said at a press event. "These new protections will make insurer obligations clearer and give homeowners more financial flexibility when they need it most."
"We are continuing to listen, act, and stand alongside the families and communities rebuilding after the Eaton and Palisades fires," Newsom said at a press event. "These new protections will make insurer obligations clearer and give homeowners more financial flexibility when they need it most."
The Palisades and Altadena fires in January 2025 destroyed 16,000 structures, including 12,000 homes, causing upward of $131 billion in property and capital losses.
Even President Donald Trump was critical of the insurers, singling out State Farm and others and calling them "horrendous" for allegedly not paying out to Californians who'd spent years paying premiums.
Mortgage and insurance reforms
Two of the bills, AB-1642 and AB-1795, create standards for smoke damage claims. California could be the first in the nation with this kind of standard, the governor said. Some 13,000 of the 40,000 home insurance claims from the Palisades and Altadena fires involved smoke-damaged homes that didn't burn.
California's Department of Toxic Substances Control and the California Air Resources Board will also develop standards for the testing and remediation of lead and asbestos contamination from wildfires. Insurers would need to pay for cleanup.
“AB-1642 will set a new national precedent on scientific standards for clearing a home for occupancy after a wildfire," Assemblymember John Harabedian (D-Pasadena) said in a statement. "Science, not an insurance company’s opinions, will determine whether a home is safe."
Two other bills, AB-1842 and AB-1847, address mortgage forbearance. The first would let homeowners in a federally declared disaster zone request a 12-month forbearance on a residential mortgage loan. That would enshrine a protection homeowners got after the wildfires. The second doubles the mortgage forbearance window available by law for L.A. fire survivors for up to two years.
 Flames from the Palisades fire burn a home during a powerful windstorm on Jan. 8, 2025, in Southern California.Apu Gomes/Getty Images The Golden State has three more pending bills that offer further insurance reforms. The Legislature passed them all last week and sent them to Newsom's desk.
SB-876 would add new requirements for insurers to handle claims more quickly in a declared emergency. It would also increase penalties for violations of fair claims practices. SB-877 is aimed at speeding the times for insurers to provide documents related to claims. SB-878 requires those insurers to provide compliance data on their payouts, starting in 2028.
The measures come as California Insurance Commissioner Ricardo Lara reviewed over 2,000 complaints from homeowners about delays and denials in insurance payouts.
...
Read the full Article Here
|
|
Home sellers may have to 'take a hit' as rates rise, real estate experts say
Fox Business
Kristin Altus
American homeowners expecting peak-market valuations are confronting a changing real estate landscape following the Federal Reserve’s latest interest rate decision.
Rising borrowing costs are shrinking the pool of qualified buyers, signaling a potential wave of price reductions for sellers seeking to close deals before year-end, real estate insiders told Fox News Digital.
"Sellers have… very high expectations. And it takes a while for sellers’ expectations to come down. And that's the reality," DaGrosa Capital Partners founder and chairman Joe DaGrosa told Fox News Digital. "With respect to buyers, I think a lot of people are going to have to wait it out. And wait and see a better situation on the mortgage front… [there’s] going to be some pressure. So I think it's going to be tough on buyers and it's going to be tough on sellers."
"Fewer buyers equals fewer opportunities to sell the home, less competitive environment. And so as a result, we're seeing a lot of sellers struggling to sell their homes in a market that otherwise would be a pretty strong market," Bowers Group Vice President at Compass Brett Rubin also said.
"And with that, we're starting to see homes sitting on the market a little bit longer, a lot more price reductions, hesitant buyers kind of sitting on their sidelines. And so this rate hike definitely has implications on both sides of the spectrum."
Federal Reserve policymakers voted 12-0 on Wednesday to raise the target range for the federal funds rate from 3.5%-3.75% to 3.75%-4%. The 25-basis-point increase marked the first interest rate hike since July 2023 and came after the Fed left rates unchanged at its first five meetings this year.
The average rate on a 30-year fixed refinance increased to 7.14% from 6.87% a week earlier, while the average 15-year fixed refinance rate was 6.30% Thursday, according to the Mortgage Research Center.
"The retail market sellers are going to realize that they've probably experienced 40%, 50% appreciation of their property values over the past 8 to 10 years… I think they're going to have to recognize that they're going to take a little bit of a hit if they want to sell," DaGrosa said. "And homebuilder sentiment is at its lowest in the past 12 months. It may get worse before it gets better. So you're seeing a double whammy for homebuilds, which is their cost of building homes has gone up."
"Some folks who need to sell their homes, they're full steam ahead as well, and they're just going to have to weather the storm for better or for worse," Rubin added. "Ultimately, if they need to reduce the price, that might be in the cards for them."
...
|
|
ANOTHER SUCCESS STORY!!!Congratulations to the Bollman's. We just set a new price for the neighborhood. Your hard work and elbow grease paid off to get this home sold. Thank you for trusting me with the sale of your first home.
|
|
What My Clients Are Saying  
|
|
Want Off Market Properties?
See all the current properties that are not yet on the market. Send us an email and we can start sending you these properties daily. Or ask us about our growing list of off market sellers.
We have a property on the Mesa and Los Carneros Village that will be coming soon. Call us for more details.
|
|
Local Market Insights This Month!
|
|
|
|
New Listings
247 homes hit the market in August
|
|
Turn Over
Anything under 4 months of inventory is considered a sellers market.
|
|
|
|
DOM
The average home is taking about 63 days to sell in August.
|
|
|
Sold Prices
Selling above 96% of the list price
|
|
|
|
|
|
|
|